The coming wave: modelling end-of-life EV battery volumes to 2035
The first mass wave of EVs is reaching end-of-first-life. We look at what that means for recoverable material, and who needs to be ready.
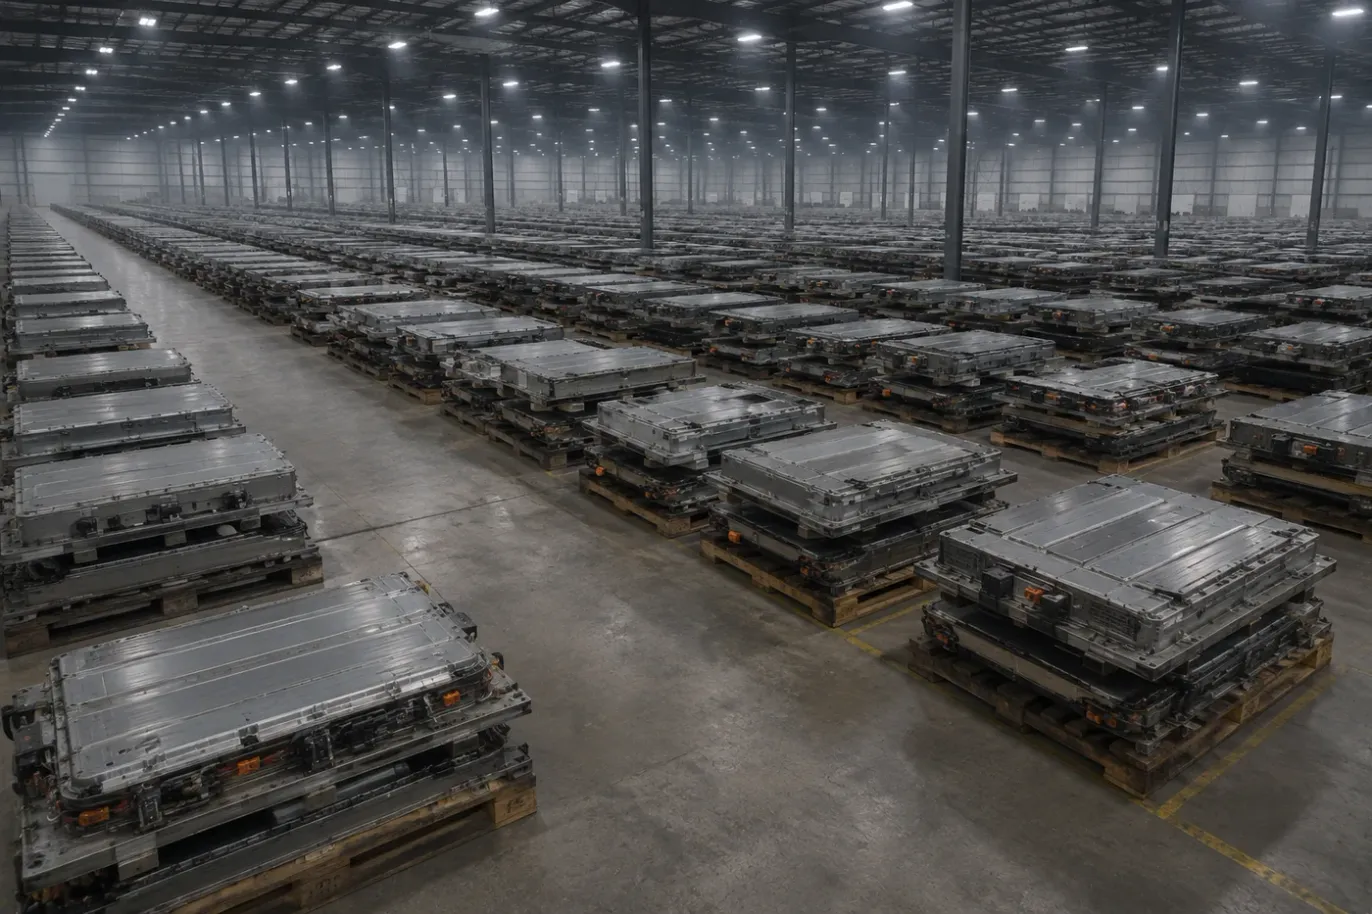
The UK’s first large cohort of electric vehicles is reaching the age where packs start coming out. The volume is arriving. The question is whether there is anywhere for it to go.
The shape of the wave
Battery retirements do not arrive evenly. They track vehicle sales roughly a decade earlier, which means the curve steepens sharply rather than rising smoothly. The UK Battery Strategy projects around 150,000 tonnes of end-of-life packs needing processing each year by 2035, and the SMMT expects around 28,000 tonnes of EV batteries to reach end of first life in the UK by 2030, rising to 235,000 tonnes by 2040.
Capacity is the binding constraint
Volume becomes a problem without processing capacity, and the gap between the two is where packs sit in yards accruing storage cost and compliance exposure.
The capacity that matters is precision capacity: the ability to take a pack apart, grade what is inside and return documentation with it. Shredding capacity is comparatively easy to add.
Who needs to be ready
Fleet operators and ATFs feel it first, because packs accumulate on their sites. Insurers feel it next, because a pack with no established residual value gets priced as a total loss. OEMs feel it in the form of producer-responsibility obligations that do not soften as volumes rise.
Each of those positions gets harder with time. The operators who have a route in place before the curve steepens are the ones who will be writing contracts rather than clearing yards.